Overdrawn bank accounts, empty company coffers - the current pandemic situation is leading to financial bottlenecks for many private households and companies. Insolvency proceedings are often the last option. However, the "end" in insolvency can also be the beginning of a new, debt-free future.
What are insolvency proceedings?
Until the 1990s, there were no insolvency proceedings for natural persons. For debtors, this often meant a lifetime of debts that they would take to their grave. It was only with the introduction of the Insolvency Code (InsO for short) in 1999 that private individuals were able to file for insolvency for the first time. The procedure is similar for private and corporate insolvency: an insolvency administrator is appointed following insolvency advice or debtor counseling.
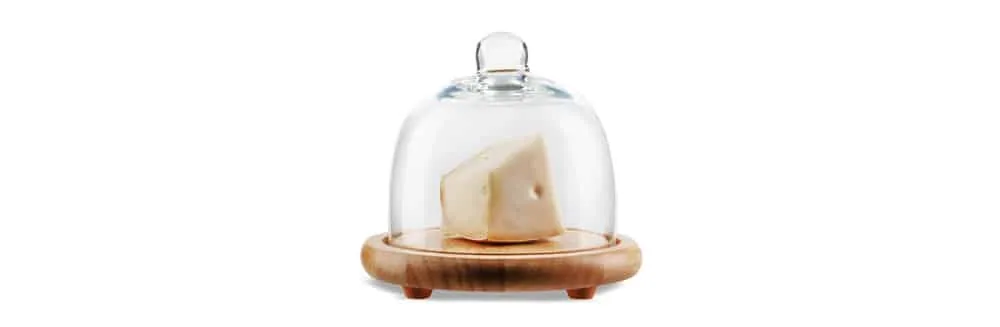
Insolvency proceedings then act like a cheese bell that is placed over the assets: Nothing goes in and nothing goes out. An insolvency administrator is appointed who distributes the remaining assets to the creditors. All creditors therefore receive a share of what is still under the cheese bell. The distribution is based on the insolvency plan drawn up by the insolvency administrator. At the end, the residual debt is discharged. The company can restart and the private individual's over-indebtedness is lifted off his shoulders after the residual debt discharge. Nothing then stands in the way of a new economic start.
That's new!
Due to the current pandemic situation, the government in Berlin has decided to make things easier for debtors and has taken the following measures:
The so-called obligation to file for insolvency has been suspended until 30.01.2021: For debtors, this means that they do not currently have to file for insolvency even if there is a threat of insolvency or over-indebtedness. Contrary to what the InsO actually provides for in insolvency proceedings, there is currently no obligation to file for insolvency immediately. It is hoped that this will enable debtors to avoid insolvency proceedings once the infection rate and the economic situation have improved again at the end of January.
Creditors therefore still have to be patient at the moment, although insolvency is often only postponed: if the economic situation has not improved by the end of January, many companies and private individuals will still be over-indebted. An insolvency application must then be filed at the latest. Just how tense the situation is for debtors at the moment is also shown by the high demand for advice and the rush to the advice centers. Particularly in consumer insolvency proceedings and under pressure from creditors, many debtors are trying to find out information now so that they can make the right decisions in January after the exemption from the obligation to file for insolvency has expired.
Further facilitations
The state fears a large number of insolvency proceedings under the InsO as a result of the pandemic, both in the area of consumer insolvency proceedings and in the area of corporate insolvency proceedings. Debtors are therefore granted the following relief:
Reduction of residual debt discharge
For insolvency proceedings filed from October 1, 2020, the residual debt discharge procedure will be shortened to three years. This means that, according to the provisions of the InsO, you will be debt-free after just three years after going through insolvency counseling and the insolvency plan. Private insolvency can therefore be over after this short time.
To protect creditors in particular, personal and corporate insolvency is subject to certain conditions:
Winnings from a lottery or prize games must be handed over to the insolvency administrator and distributed to the creditors. Another new feature of the InsO is that you can only file for insolvency once every 11 years. This is intended to protect creditors from debtors who often find themselves in an insolvency situation - probably through their own fault. Debt counselling services usually point this out right at the beginning of a consultation: only when it is clear that all creditors can no longer be satisfied and there are "sufficient" debts should the one-off option of filing for insolvency be taken. If the debts are small and still serviceable, debtor counselors will tend to advise against insolvency under the InsO. This is because in many cases, insolvency can be avoided following insolvency advice or debtor counseling, e.g. through payment plans with creditors. Insolvency proceedings can then be averted and a full discharge of residual debt is no longer necessary.
The current changes also show that the legislator wants to give every debtor a fair second chance. This is particularly true in the current situation of the global pandemic, which has led to a massive slump in sales in certain sectors.
Recht 24/7 provides advice from specialist lawyers in insolvency law as part of an initial consultation. Please send us your request to service@recht24-7.de.